Roof Damage Appraisal Process in Texas

When you and your insurer disagree on the amount, a detailed estimate and photos give your appraiser something to work with.

Get a Free InspectionCall 512-271-6893 5 Stars on GoogleBBB AccreditedFully Insured
INSURANCE CLAIMS

Disagree With the Amount? Appraisal Can Settle It.

When your insurer agrees there’s damage but not on what it costs to fix, appraisal is a way to settle the number without a lawsuit.

Sometimes an insurance company accepts a roof claim but pays far less than the repair will cost: slopes that were never inspected, missing line items, or a repair-only estimate on a roof that can’t be repaired. When the dispute is about the amount, Texas homeowners have a tool for it: the appraisal process.

Appraisal only works as well as the evidence behind it. We inspect the roof, photograph the damage slope by slope, and write a detailed repair estimate that you and your appraiser can use.

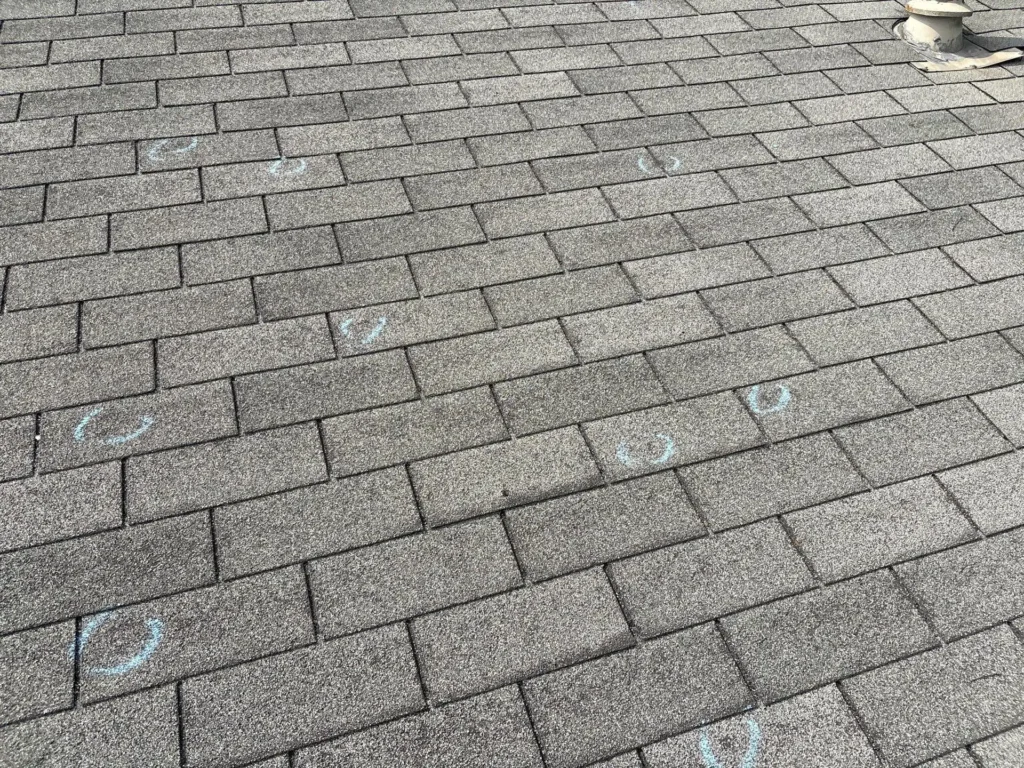
Hail impacts circled in blue chalk on gray asphalt shingles during a roof inspection in Georgetown, TX

All Insurance Companies

We work with every carrier

Free Inspections

Always, with no obligation

BBB Accredited

Local and accountable

Fully Insured

Protection on every job

Is Appraisal the Right Path?

Appraisal settles one question: how much the covered damage costs to repair. It works well for some disputes and not at all for others.

Your claim was accepted

Appraisal starts from a covered loss. If the insurer agreed there’s storm damage but you disagree on the payment, it fits.

Damage was left out

The estimate skipped slopes, flashing, vents, gutters or other damaged parts. A detailed, line-by-line estimate shows what’s missing.

Repair versus replace

The insurer priced a repair, but the damage is spread across the roof or the material can’t be matched. That may be an amount question for your appraiser.

Your claim was denied

If the insurer says the policy doesn’t cover the damage at all, appraisal won’t decide that. See what to do after a denial.

Storm or wear and tear?

Disputes about what caused the damage are generally coverage questions, not amount questions, so appraisal usually can’t settle them.

A small difference

You pay your own appraiser and usually share the umpire’s fee. If the gap is small, those costs can outweigh what you’d gain.

Every policy is different. The appraisal section of your policy, and your agent, can tell you what applies to you.

How the Appraisal Process Works

Most Texas homeowners policies follow these steps. Your policy sets the exact deadlines.

01

Written Demand

You or your insurer asks for appraisal in writing.

02

Each Side Picks an Appraiser

Each side hires its own competent, disinterested appraiser.

03

Appraisers Pick an Umpire

The appraisers choose a neutral umpire. If they can’t agree, a court can appoint one.

04

Estimates Are Compared

Each appraiser sets the amount of loss, and they try to agree.

05

The Award

An agreement by two of the three sets the amount, and it binds both sides.

Where We Fit In

Appraisal is between you, your insurer and the appraisers. Our job is the roof.

What we do:

What we don’t do:

Texas Specialty Roofing is not a public insurance adjuster and does not provide public adjusting services. We don’t negotiate claims or represent policyholders on coverage. Coverage decisions are made by your insurance company.

What Texas Law Says About Appraisal

A 2025 state law made appraisal a standard part of Texas homeowners policies. TDI has proposed rules on deadlines and appraiser qualifications; until they’re final, your policy sets the details.

Required in New Policies

Under Texas Insurance Code Chapter 1813 (Senate Bill 458), residential property policies issued or renewed on or after January 1, 2026 must include an appraisal provision. TWIA and commercial policies are excluded.

Amount of Loss Only

Appraisal is solely to set the amount of loss when that amount is in dispute. It doesn’t change your policy terms or decide whether the damage is covered.

The Award Is Binding

The award binds you and your insurer, with narrow exceptions such as fraud, a material mistake, or an award made without authority. See TDI’s guide to claim disputes.

Free  ·  No obligation  ·  Before or during appraisal

Get Your Roof Documented

Tell us about the storm and where your claim stands. We’ll inspect the roof and the attic, photograph what we find, and write a detailed repair estimate you can give your appraiser.

Prefer to call? Round Rock 512-271-6893 · San Antonio 210-512-4132

Tell Us About the Storm

This sends a request, not a booked time. We’ll call you to set one up.

Not sure it was hail? Try our hail damage checker.

Prefer to call? Round Rock 512-271-6893 · San Antonio 210-512-4132

Helpful Next Steps

Claim Denied?

Your options when the insurer says no.

Hail Damage Checker

Answer a few questions to see what your answers suggest.

How Roof Insurance Claims Work

Step by step, from inspection to finished roof.

Roof Damage Appraisal Questions

It’s a section of your policy that lets you or your insurer settle a disagreement about the amount of loss. Each side picks an appraiser, the appraisers pick an umpire, and an agreement by two of them sets the amount.

Texas law requires one in residential property policies issued or renewed on or after January 1, 2026, and many older policies have one too. Look in the conditions section of your policy, or ask your agent.

You pay your own appraiser, and you typically split the umpire’s cost with your insurer. Check your policy for the exact terms.

Not by itself. Appraisal sets the amount of a covered loss; it doesn’t decide coverage. If your claim was denied, see what to do after a denied roof claim.

Appraisers have to be disinterested. A roofer who would do the repair has a stake in the outcome, so we don’t serve as appraisers. We give your appraiser our photos and estimate instead.

It depends on the policy, the appraisers and the size of the claim. TDI has proposed rules that would set deadlines for each step; until they’re final, your policy’s appraisal section sets the timeline.

Generally, yes. Texas law makes the award binding on you and your insurer, except in narrow cases such as fraud, a material mistake, or an award made without authority.

Disputing the Amount? Start With Better Evidence.

We’ll inspect your roof, document every slope, and write a detailed repair estimate you can share with your appraiser.