RESIDENTIAL OR COMMERCIAL
Insurance Claims Made Easier
We work with all insurance companies, so the process is less stressful for you.
Storm damage? Hail? Wind? Dealing with an insurance claim can feel overwhelming, but you’re not on your own. At Texas Specialty Roofing, we guide homeowners and business owners through the process, from the first inspection to the finished roof.
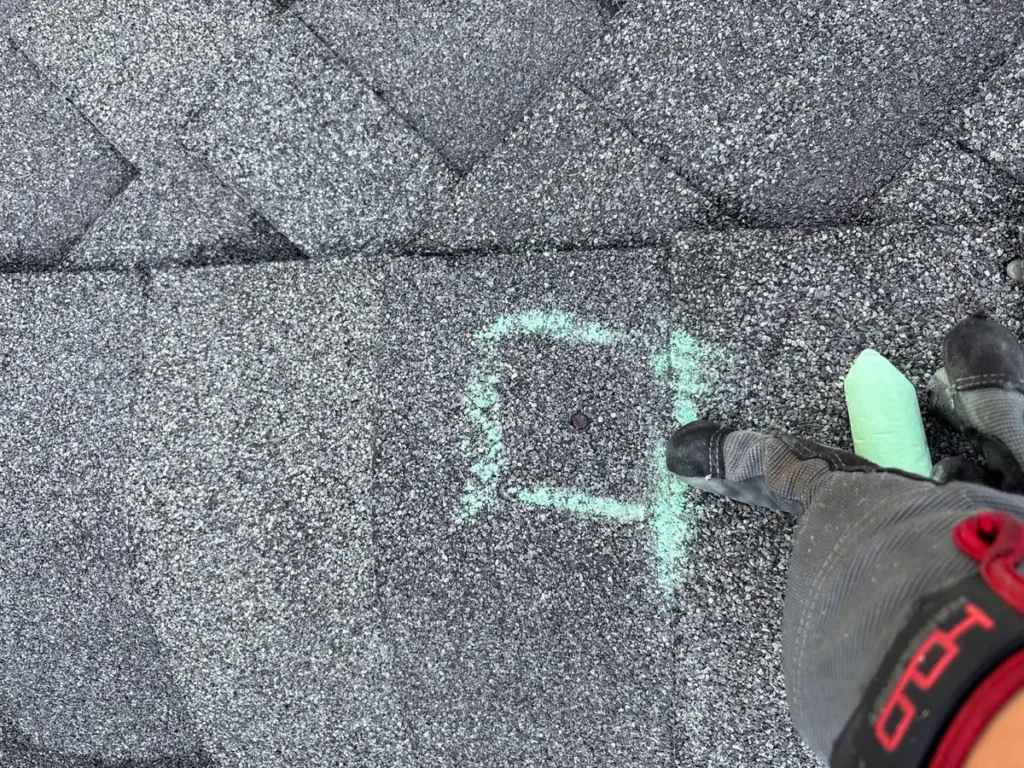
We inspect and document the damage, give you a detailed repair estimate, and can meet your insurance adjuster at the property to show them what we found and walk through what the repair involves. You always know where things stand and what comes next.
All Insurance Companies
We work with every carrier
Free Inspections
Always, with no obligation
BBB Accredited
Local and accountable
Fully Insured
Protection on every job
Help With Residential and Commercial Claims
Whether it’s your home or your business, we handle the roofing side of the claim with the same care.
For Homeowners
A storm can damage your roof, gutters, fence, and more all at once. We document everything we find, explain your options in plain language, and coordinate the work so you’re not juggling several contractors.
For Businesses and Property Owners
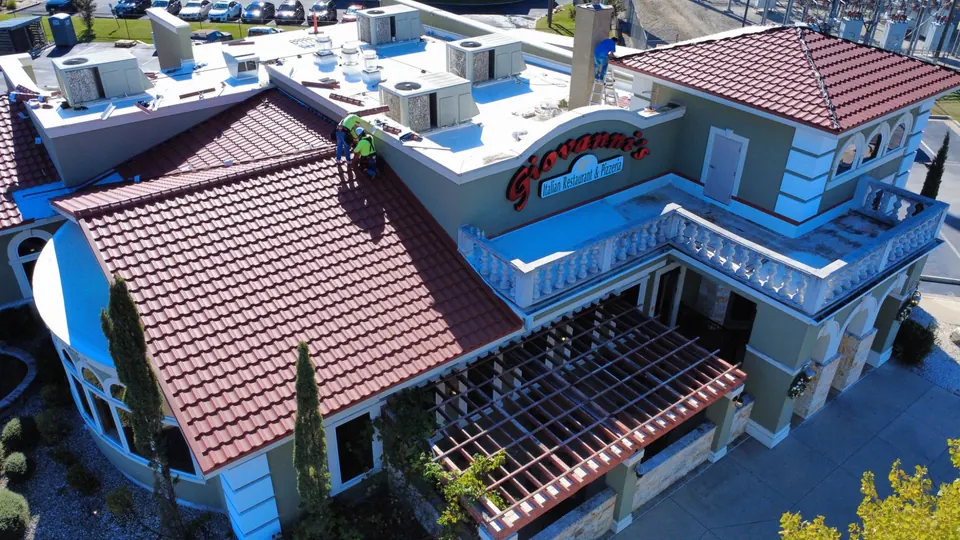
For businesses, churches, multi-family properties, and assisted living facilities, we document the damage, provide clear estimates for your insurer and your team, and plan the work around the people who use the building.
How the Insurance Process Works
Every claim is different, but most follow these steps. We’ll tell you what to expect at each one.
01
Free Inspection
We inspect your roof and property and document the damage with photos, before you file.
02
You File the Claim
If there’s real storm damage, you report it to your insurance company.
03
Adjuster Visit
The adjuster inspects the damage. We can be there to show what we documented.
04
Review the Estimate
When you get the insurer’s estimate, we explain what the repair involves.
05
Repair and Close Out
We do the work and give you the final invoice and photos your insurer may need.
Who Does What
Knowing who handles each part of a claim avoids surprises. Here’s how it breaks down.
What we do:
- Inspect your roof for free and tell you honestly what we find
- Document the damage with photos and notes
- Give you a detailed, written repair estimate
- Meet your adjuster at the property if you’d like
- Explain the insurer’s estimate in plain language
- Do the work and provide your final invoice and photos
What stays with you and your insurer:
- Filing the claim and talking with your insurance company
- Coverage decisions and the claim settlement
- Paying your deductible, which Texas law requires
- Questions about your policy, for your agent
Texas Specialty Roofing is not a public insurance adjuster and does not provide public adjusting services. We don’t negotiate claims or represent policyholders on coverage. Coverage decisions are made by your insurance company.
Before You Call Your Insurance Company
A few simple steps now can make the whole claim go more smoothly.
Write down the storm date
Note the date and time of the storm. Your insurer will ask, and it helps tie the damage to a specific event.
Take photos from the ground
Photograph damage you can safely see: gutters, vents, siding, windows, fences, and any ceiling stains inside. Please stay off the roof.
Prevent more damage
If water is getting in, protect your home and keep receipts for any emergency repairs. Need help now? See emergency roof repair.
Get an inspection first
Knowing whether there’s real roof damage before you file helps you make an informed decision about your claim.
Check your policy
Look for your deductible and any deadlines for reporting storm damage. If you’re not sure, ask your agent.
Insurance Terms, Explained
Claim paperwork has its own language. Here’s what the most common terms mean.
Deductible
The amount you pay before insurance pays. Some Texas policies use a percentage for wind and hail.
Actual Cash Value (ACV)
Pays the value of your roof after depreciation for age and wear.
Replacement Cost Value (RCV)
Covers the cost to replace the roof, often paid in two parts.
Recoverable Depreciation
On many RCV policies, the amount held back until the work is finished and invoiced.
Scope of Loss
The insurer’s list of the damage and the work its estimate covers.
Cosmetic Damage Exclusion
Some policies don’t cover dents that don’t affect how a roof performs, most often on metal.
Every policy is different. Your agent can tell you exactly what yours includes.
Know the Law Before You Sign
Texas has clear rules for roofers and insurance claims. They protect you, and we follow them.
Your Deductible Is Yours
It’s illegal in Texas for a contractor to waive, rebate, or absorb your deductible, and your insurer can ask for proof that you paid it. If a roofer offers to cover it, walk away.
Roofers Can’t Be Your Adjuster
A contractor doing the work on your property can’t act as a public adjuster, negotiate your settlement, or claim to represent you with your insurer. Be wary of anyone who promises to.
Watch for Storm Chasers
High-pressure sales, promises to get you “every dollar,” and big upfront payments are red flags. Choose a local company with a real office. Learn more from the Texas Department of Insurance.
A REAL CLAIM
One Storm, One Team, One Plan
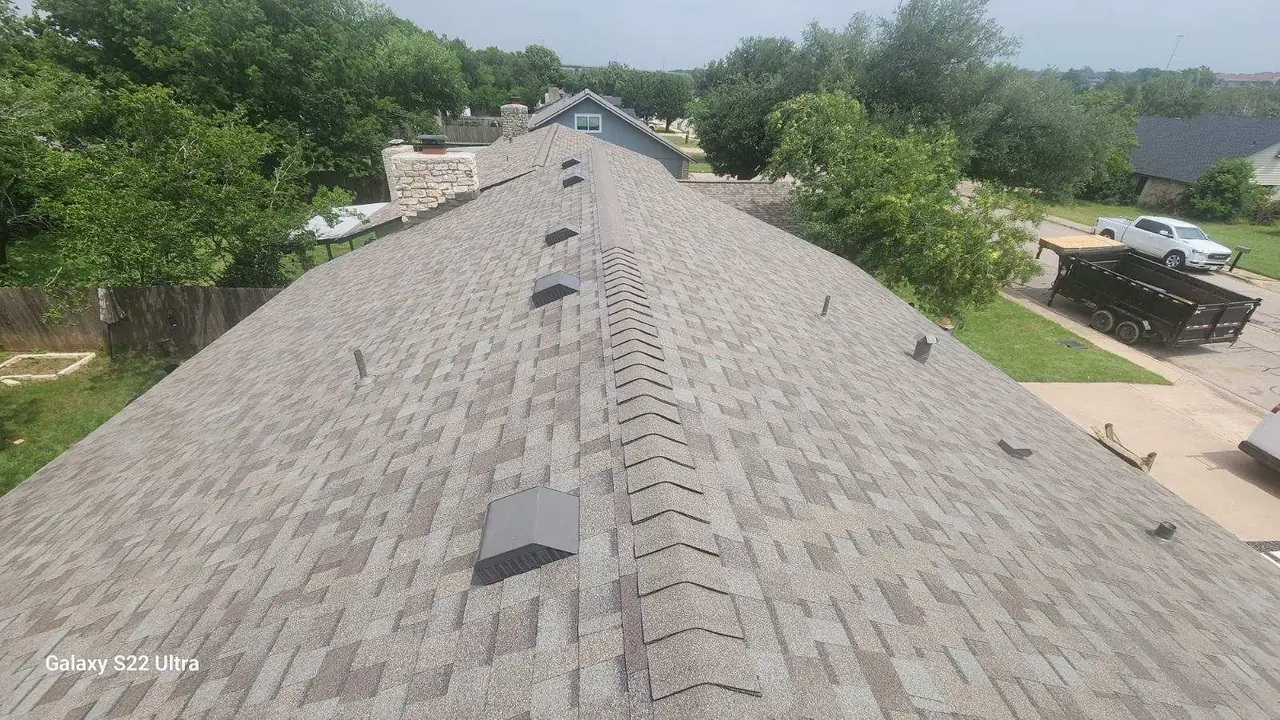
A major hail storm damaged Brandon’s roof in Round Rock, along with his gutters, garage door, and fence. His roof was only a few years old. We documented the damage, and the claim was approved for a full roof replacement. Then we coordinated the roof, gutters, garage door, and fence, so he had one team handling all of it.
Every claim is different, and the outcome depends on the damage and the policy.
Helpful Next Steps
Storm Damage Roof Repair
Hail and wind damage repair, from inspection to finished roof.
Hail Damage Checker
Answer a few questions to see what your answers suggest.
Emergency Roof Repair
Active leak after a storm? Get help protecting your home.
Roof Insurance Claim Questions
Should I call my insurance company or a roofer first?
We recommend a free inspection first. That way you know whether there’s real roof damage before you file. If there is, you can report it to your insurer with photos and a clear picture of what happened.
Do you work with my insurance company?
Yes. We work with all insurance companies, for both residential and commercial properties.
Will you meet with my adjuster?
Yes, if you’d like us to. We can be at the property during the adjuster’s inspection to show the damage we documented and explain what the repair involves.
Can you negotiate my claim for me?
No. Texas law doesn’t allow a contractor who is doing the work to act as a public adjuster or negotiate a settlement for you. We handle the roofing side: inspection, documentation, estimates, and the work itself. If you want someone to represent you on the claim, you can hire a licensed public adjuster or an attorney.
Can you pay or waive my deductible?
No. It’s illegal in Texas for a contractor to waive, rebate, or absorb a deductible, and your insurer can ask for proof that you paid it. A roofer who offers to cover it is breaking the law.
What if my claim is denied or the estimate seems low?
You can ask your insurance company to explain the decision in writing and ask about a reinspection. We can give you our documentation and repair estimate to share. If you want help disputing a claim, a licensed public adjuster or an attorney can represent you, and the Texas Department of Insurance has a consumer help line.
What if the damage costs less than my deductible?
We’ll tell you. If the repair is likely to cost less than your deductible, filing a claim may not make sense, and we’ll give you a straightforward repair estimate instead.
Will filing a claim raise my premium?
It depends on your insurance company and policy. Your agent is the best person to ask.
How long does the claim process take?
It varies with the insurer, the size of the storm, and how busy adjusters are. We’ll keep you updated at each step and schedule your work as soon as the claim is approved.
Storm Damage? Start With a Free Inspection.
We’ll inspect your roof, document what we find, and help you understand your options before you file.
Texas Specialty Roofing is not a public insurance adjuster and does not provide public adjusting services. We don’t negotiate claims or represent policyholders on coverage. Coverage decisions are made by your insurance company.