Roof Insurance Claim Denied in Texas

A denial isn’t always the last word. Start with a free second inspection and clear photo documentation.

Get a Free InspectionCall 512-271-6893 5 Stars on GoogleBBB AccreditedFully Insured
AFTER A DENIED CLAIM

Denied Doesn’t Always Mean Done

A denial isn’t always the last word. Start with a second look at your roof.

A denied roof insurance claim is frustrating, especially when you can see the damage from your driveway. But in Texas, a denial isn’t necessarily final. Your insurance company has to tell you in writing why it said no, and that letter is where your next step starts.

We give you a free second inspection, check every slope and the attic, and photograph what we find. If the damage is real, you get clear documentation and a written repair estimate you can send to your insurer. If it isn’t, we’ll tell you that too.

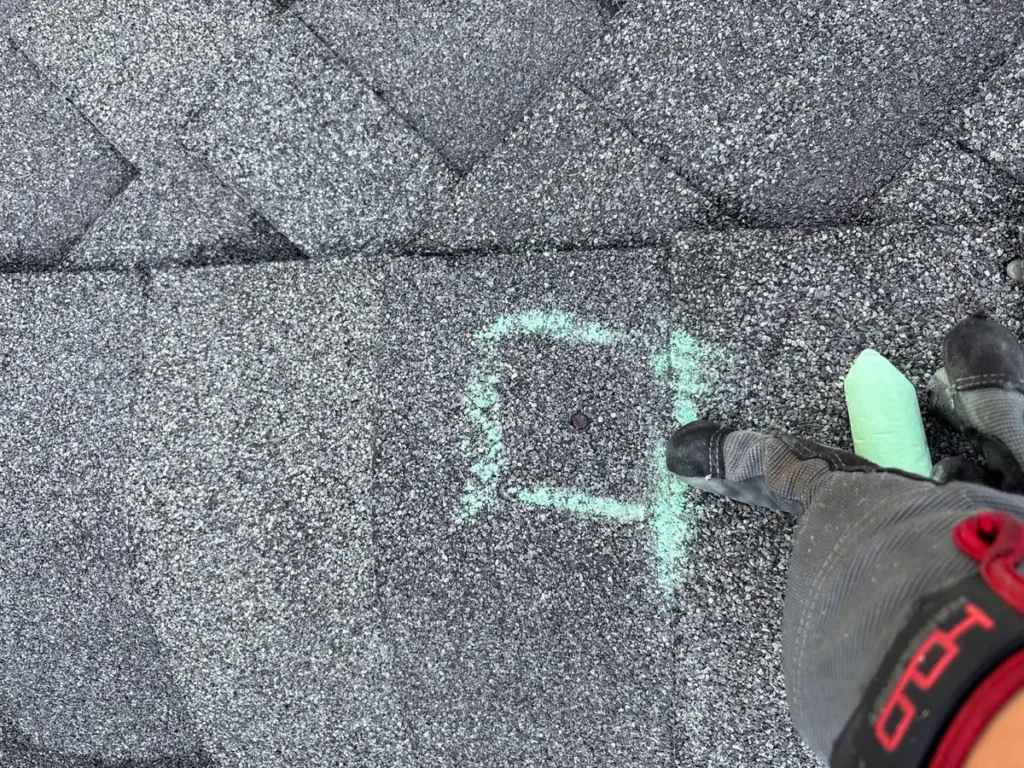
Green chalk box highlighting a small shingle damage point during roof inspection documentation.

All Insurance Companies

We work with every carrier

Free Inspections

Always, with no obligation

BBB Accredited

Local and accountable

Fully Insured

Protection on every job

Common Reasons Roof Claims Get Denied in Texas

Most denial letters come down to a few explanations. Knowing which one you got tells you what kind of evidence would matter.

Wear and tear or age

The adjuster decided the damage came from age, heat or normal wear. Clear photos of fresh hail hits, torn shingles and dented metal can show what actually happened.

Below your deductible

Many Texas policies use a percentage deductible for wind and hail. A detailed, line-by-line estimate can show whether something was missed.

Cosmetic damage exclusion

Some policies don’t pay for dents that don’t affect how the roof performs, most often on metal. Close-up photos help show the difference.

Not tied to a storm

If the insurer can’t connect the damage to a specific storm, or thinks it was reported late, it may deny the claim. Dates and dated photos help.

Damage that was missed

A quick inspection can miss damage on back slopes, in valleys, or on vents and flashing. A full, slope-by-slope look often finds more.

An excluded cause

Policies don’t pay for some causes of damage, such as flooding. The letter should name the exclusion it relies on.

Not sure what hail damage looks like? See our hail damage roof guide.

Your Options If Your Roof Claim Was Denied

Every claim is different, but most homeowners work through these steps, roughly in this order.

01

Read the Denial Letter

Find the exact reason and the policy section it cites. Texas law requires the reason in writing.

02

Get a Second Inspection

We inspect every slope and the attic and photograph what we find, for free.

03

Send New Evidence

Send our photos and estimate to your insurer and ask it to reconsider or reinspect.

04

Ask About Appraisal

If you and your insurer disagree on the amount of loss, your policy’s appraisal clause may apply.

05

Get Outside Help

Still think it’s wrong? File a complaint with TDI, or talk to a licensed public adjuster or attorney.

How We Help After a Denial

Texas law limits what a roofer can do on an insurance claim, and we follow it. Here’s where we fit in.

What we do:

What stays with you and your insurer:

Texas Specialty Roofing is not a public insurance adjuster and does not provide public adjusting services. We don’t negotiate claims or represent policyholders on coverage. Coverage decisions are made by your insurance company.

Know Your Rights After a Denial

Texas law gives policyholders a few clear protections when a claim is denied.

The Reason Must Be in Writing

Under Texas Insurance Code §542.056, your insurer must tell you in writing whether it accepts or rejects your claim, generally within 15 business days of receiving everything it asked for. If it rejects the claim, the notice must state the reasons.

Appraisal Is an Option

Texas law now requires an appraisal clause in residential property policies issued or renewed since January 1, 2026. It settles disagreements about the amount of loss, not coverage. How appraisal works.

TDI Can Step In

If you think your claim was unfairly denied, you can file a complaint with the Texas Department of Insurance, and TDI can ask your insurer to review its decision. Call 800-252-3439 or read TDI’s guide.

Free  ·  No obligation  ·  After a denial

Request a Free Second Inspection

Tell us about the storm and what your denial letter says. We’ll inspect the roof and the attic, photograph what we find, and tell you honestly whether we see storm damage worth sending back to your insurer.

Prefer to call? Round Rock 512-271-6893 · San Antonio 210-512-4132

Tell Us About the Storm

This sends a request, not a booked time. We’ll call you to set one up.

Not sure it was hail? Try our hail damage checker.

Prefer to call? Round Rock 512-271-6893 · San Antonio 210-512-4132

Helpful Next Steps

How Roof Insurance Claims Work

Step by step, from first inspection to finished roof.

Hail Damage Checker

Answer a few questions to see what your answers suggest.

Emergency Roof Repair

Active leak after a storm? Get help protecting your home.

Denied Roof Claim Questions

Yes. Start by asking your insurance company to reconsider, and send any new evidence, such as photos and a contractor’s repair estimate. You can also ask for a reinspection. If you still disagree, you may be able to request appraisal or file a complaint with the Texas Department of Insurance.

Under Texas Insurance Code §542.056, an insurer generally has 15 business days after it receives everything it asked for to accept or reject your claim in writing. If it needs more time, it has to tell you why, and then decide within 45 days.

Yes. A second inspection is free, with no obligation. We’ll tell you honestly what we see, including if we don’t find storm damage.

No. Texas law doesn’t allow a contractor doing the work to act as a public adjuster or negotiate a settlement for you. We provide the inspection, photos, and estimate. You, or a licensed professional you choose, handle the claim itself.

That’s your call. For a large or complicated denial, a licensed public adjuster or an attorney who handles insurance disputes can review your policy and your options. We’re glad to share our documentation with whoever you choose.

Ask for the insurer’s estimate and compare it with a detailed repair estimate. If items were missed, send the new estimate with photos. If the damage really is under your deductible, we’ll give you a straightforward repair price. And in Texas, a roofer can’t waive or cover your deductible.

Your policy sets deadlines for things like reporting damage and filing a lawsuit, and they vary. Check your policy or ask your agent soon after you get the denial, rather than waiting.

Claim Denied? Get a Free Second Look.

We’ll inspect your roof, document what we find, and give you an honest answer about what to do next.